Freitag, 18. Mai 2012

The two factors weighing on markets

Financial markets have been determined by the "risk on or off" argument for 4 years. Fundamental market analysis does not count in this environment. Last year the meltdown in stock prices was caused by a deterioration of the Euro crisis and was saved in autumn by massive liquidity injection of the ECB (twice € 500bn). This summer we have even two potential areas of infection:

  1. The situation in Greece might trigger contagion. Equity markets already have discounted a deterioration in Greece.
  2. Some people think that Israel might attack Iran soon. Reuters published an article today. The article states, that Bibi is determined and the window of opportunity is closing fast. Furthermore, experts have problems to read the Israeli signals properly.
Since March, we have been in a situation of great uncertainty. And markets hate uncertainty. However,
should it be clear that those scenarios are false, markets will rally. Should one of the two worst case scenario come true, markets will dive. In the meantime they are volatile and under pressure.


Dienstag, 3. April 2012

BCA: Not much growth in the US and elsewhere

BCA just came out with their monthly forecast for April 2012:
  • US economy will not grow strongly (contrary to market perception). Although the housing market has bottomed, lacking household income growth, looming fiscal restraint, and rising gas prices will dampen growth. As a consequence...

    In the long term inflation will pick up if the economy is getting stronger and the Fed is missing the exit point. Also, the number of experts who think that a bit of inflation would be helpful to get public debt down is increasing!
  •  Eurozone: Portugal may be next in the Euro crisis. But Spain's banks are heavily engaged in Portugal, which allows the crisis to affect the whole Iberian peninsula. It is not difficult to see the crisis spreading further to Italy and then France.
    The ECB will be forced to keep interest rates very low for the next 3 to 5 years, which is supportive for the Dollar and Gold.
  • China: Although housing is continuing to weaken, BCA thinks that the economy will land softly. Mainly because Chinese homeowner are not leveraged (mortgage loans are 15% of GDP compared to 64% in the US). Hong Kong experienced a huge housing bust in the 90s without taking its economy down.


    Also the government would inject capital into their state owned banks if necessary.
  • Equities: Although the equity risk premium is very high, which suggest that equities are under valued....

    this is only true in relation to bonds, which are super expensive, yielding historic low. So don't expect a bull market.
  • Bonds: Yields will stay low for the next 2-3 years.

Profit Margins: What Goes Up, Must Come Down!

Profit margins may get squeezed by austerity

US asst manager GMO published a commentary about historically high profit margins by Charles Montier titled "What Goes Up, Must Come Down" and explains some interesting details:
  • Profit margins are on historical highs (and Wall Street analysts still forecast increasing margins)


  • Driver of the surge in profit margins were a combination of strong demand due to high government spending which and of decreased costs due to lower wages (globalization and outsourcing).
 
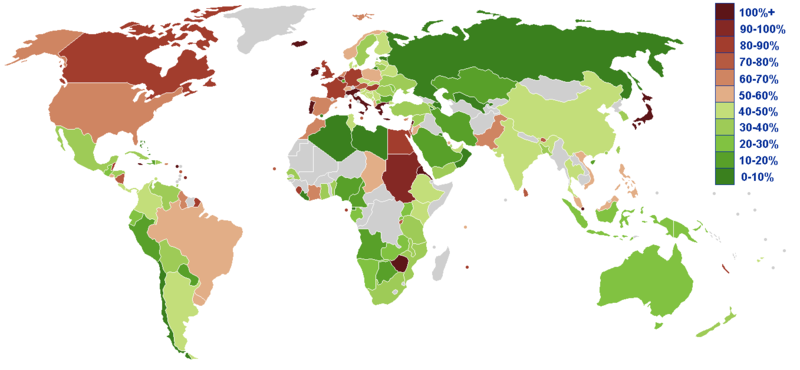
Public debt world map from Wikipedia
In many developed countries, public debt is sky high. Wikipedia has a nice list of every countries public debt.

Conclusion
In the medium term, we are stepping towards fiscal consolidation, since public debt levels are not sustainable in the long run. Hence, we have to expect that profit margins will revert to the mean (as they always did). That will spell a huge disappointment for stock holders!